Manhattan Cocktail Recipe
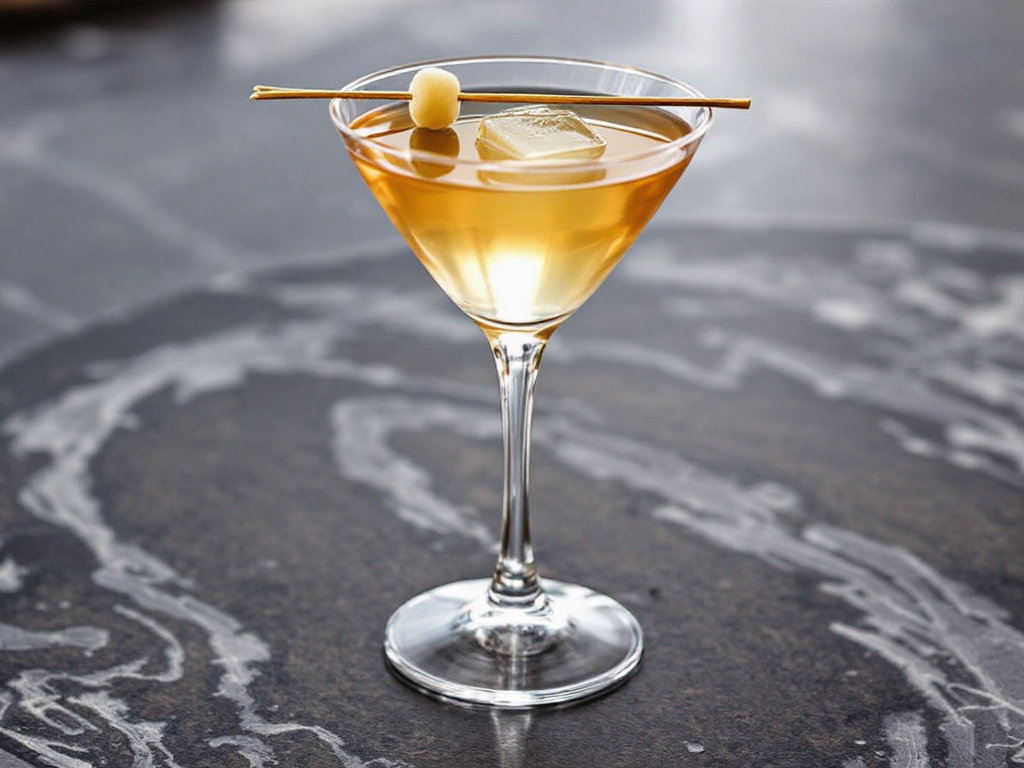
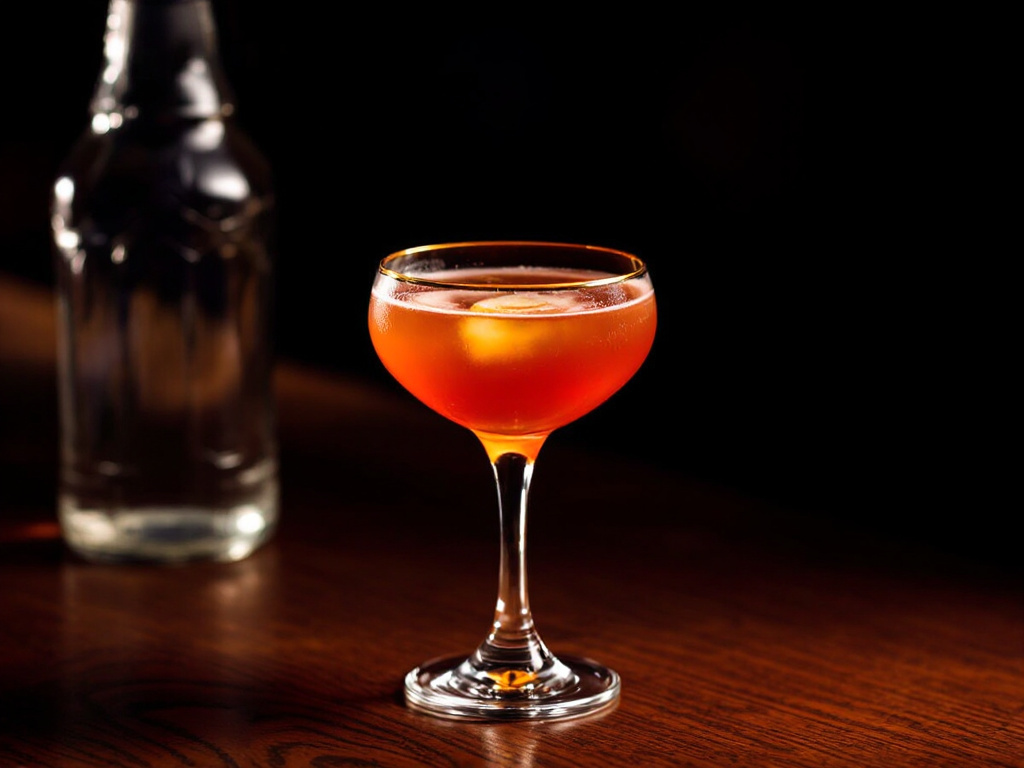
The Manhattan cocktail recipe blends rye or bourbon whiskey with sweet vermouth and aromatic bitters, stirred over ice and served in a chilled coupe with a maraschino cherry. This classic serves as a lens for exploring how precision, ambiguity, and decision-making shape both bartending and broader behaviour, including how taxpayers respond to uncertain rules.
In this guide
Key Takeaways
- Tax policy uncertainty influences taxpayer decisions, corporate planning, and government revenues in profound ways.
- Higher perceived uncertainty typically reduces tax planning investment while raising cash holdings and tax risk.
- Strategic ambiguity in enforcement can boost compliance more effectively than explicit penalty warnings.
- Peer signals about confusion can erode tax morale, giving people an excuse to be less diligent.
- Some tax uncertainty is socially desirable, functioning as a screening device that improves efficiency.
The Classic Manhattan Cocktail Recipe and What It Teaches Us
I’ve always thought the Manhattan cocktail is a lesson in balance. Two ounces of rye whiskey, one ounce of sweet vermouth, and two dashes of Angostura bitters, stirred with ice for around 30 seconds. Strain into a chilled coupe and garnish with a maraschino cherry. Precision matters, but so does judgement.
Just as a bartender balances strong spirits with sweet vermouth, taxpayers and firms constantly balance opportunity with risk. Moreover, both scenarios involve unknown outcomes and require confident decisions. I find the parallel instructive, especially when considering how uncertainty shapes behaviour in surprising ways. For fans of aperitifs, my Aperol Spritz recipe guide offers a lighter contrast.
Understanding Tax Policy Uncertainty and Behavioural Concepts
Tax policy uncertainty refers to uncertainty about future tax rates, rules, enforcement priorities, and legal interpretations. It arises from frequent legislative changes, ambiguous rules, and unresolved disputes. Consequently, taxpayers face not just known risks but unknown probabilities of audit and litigation.
Older compliance models assumed people knew the odds of being audited. However, newer research explicitly incorporates unknown audit probabilities, which better reflects real-world decisions. Most individuals are uncertainty-averse, meaning they dislike gambles with unclear odds even more than gambles with clear odds.
Here’s how a certain versus uncertain tax environment compares along key dimensions:
- Audit probability: known and stable versus unknown and shifting
- Rule clarity: precise definitions versus ambiguous interpretations
- Rate predictability: stable future rates versus frequent legislative changes
Picture a self-employed taxpayer mixing a Manhattan while reviewing ambiguous expense rules. She can’t tell whether her home-office deduction will survive a challenge. That everyday uncertainty, therefore, sits at the centre of modern tax research.
Corporate Tax Planning Under Uncertainty
Firm-level evidence tells a clear story. The study “Tax Policy Uncertainty and Investment in Tax Planning: Firm-Level Evidence”, covering U.S. firms from 2003 to 2019, found that rising tax policy uncertainty reduces tax planning investment. Consequences include lower planning effectiveness, higher tax risk, more cash holdings, and lower firm value.
The European Commission’s “Tax Uncertainty: Economic Evidence and Policy Responses” paper reports similar effects on real investment. Tax savings from aggressive planning can boost R&D and fixed asset investment, but only up to a point. Beyond that threshold, uncertainty dampens investment noticeably. Furthermore, multinationals often delay projects in jurisdictions where rules feel unstable.
Here’s a comparison across low and high uncertainty environments:
- Tax planning level: higher under low uncertainty; reduced under high uncertainty
- Cash holdings: normal versus elevated as a buffer
- Effective tax rate volatility: stable versus swinging
- Investment in tangible and intangible assets: steady versus delayed
Consider a Manhattan cocktail bar owner running as a sole trader. In some years, she claims every plausible deduction; in others, she plays safe because HMRC guidance seems unclear. Her switching behaviour mirrors what firms do when facing tax liability uncertainty over successive rounds.
Compliance, Enforcement, and the Paradox of Strategic Ambiguity
Experimental studies show taxpayers respond to uncertainty in mixed ways. Sometimes they become more conservative, reporting higher income and claiming smaller deductions. Sometimes they push harder, particularly when audit costs are high. Behaviour depends on risk attitudes, penalty rates, and whether tax structures are progressive or proportionate.
A remarkable UK field study with 204,936 taxpayers found that non-specific enforcement messages increased payment rates by up to five percentage points. Detailed deterrent messages listing specific penalties, however, had no significant effect. Ambiguity, it turns out, outperformed transparency.
Why does this happen? Taxpayers fill in the blanks and imagine severe consequences. Eye-tracking and pupillometry evidence shows that enforcement uncertainty triggers emotional stress responses, revealing an affective side to uncertainty aversion. Additionally, explicit penalties only boost compliance when they exceed what people already fear.
Here’s how the two communication styles compare:
- Ambiguous threats: higher compliance, stronger psychological impact, more administrative flexibility
- Explicit penalties: mixed compliance results, limited emotional response, less flexibility
Peer Signals and Tax Morale
A German randomised survey experiment, “Are Your Tax Problems an Opportunity Not to Pay Taxes?”, found that telling people others are confused about filing decreases individual tax morale. Negative peer signals become an excuse to opt out of full compliance, and the effects persist over time.
Imagine someone hearing that “everyone’s confused about the new rules.” They then feel justified in being less diligent. It’s the same social logic behind a casual gathering where nobody follows the exact manhattan cocktail recipe because “no one else bothers either.” Therefore, tax authorities should avoid framing that highlights widespread confusion.
The CEU Framework Explained Simply
Modern models use certainty equivalent utility (CEU) to describe decisions under unknown probabilities. In plain terms, an uncertainty-averse taxpayer compares the utility of taking a tax position against not taking it, applying a mental penalty for ambiguity. Increases in audit probability, penalty rate, or risk aversion typically push people towards more conservative reporting.
Declining absolute risk aversion also matters. As wealth grows, people become less sensitive to fixed losses, which shapes optimal deduction choices. Under common U.S. parameters, unless taxpayers are highly risk-averse, greater income uncertainty tends to reduce reported income. For a similarly structured drinks comparison
Sources:
Tax Policy Uncertainty and Investment in Tax Planning: Firm-Level Evidence
Tax Uncertainty: Economic Evidence and Policy Responses
Strategic uncertainty in tax enforcement: How ambiguity shapes compliance
The Effect of Audit Costs on Taxpayer Decisions Under Uncertainty: Evidence from the Laboratory
Tax Uncertainty and Welfare-Improving Tax Disputes
Modeling Uncertainty in Tax Law
Taxpayer compliance under uncertainty
Are Your Tax Problems an Opportunity Not to Pay Taxes? Evidence From a Randomized Survey Experiment
Certain Effects of Uncertain Taxes
What creates tax uncertainty? Evidence from three phases
Does an uncertain tax system encourage ‘aggressive tax planning’?
Advancing Tax Administration
European Commission Taxation Paper
Internal Revenue Service (IRS)